Islamic personal financing in everyday vocabulary
Islamic personal financing structures cash needs through Shariah contracts rather than conventional interest loans, with disclosed profits and asset-based steps that banks document carefully. Shoppers should read the contract name, the profit rate expression, and the early settlement rules before comparing only the monthly instalment. Affordability still follows income and existing commitments, regardless of branding on the brochure.
Product pages for personal financing facilities outline eligibility themes and documentation. Treat them as maps to banker conversations, not as approval promises typed in advance.
Bank Negara Malaysia supervises Islamic banking conduct and publishes consumer education materials. The Malaysia International Islamic Financial Centre resources help readers understand the wider Islamic finance ecosystem. Use both for literacy, then verify every figure against your letter of offer.
Term deposits as a separate decision
Saving products such as term deposit accounts answer a different question: parking surplus funds for a fixed period with disclosed profit arrangements. Do not fund a financing application by breaking a deposit without calculating opportunity cost and penalties that may apply.
Ladder maturities if you may need staggered liquidity. A single long tenure is inflexible when family expenses arrive unevenly across school terms and festive months.
Motorcycle financing as a focused use case
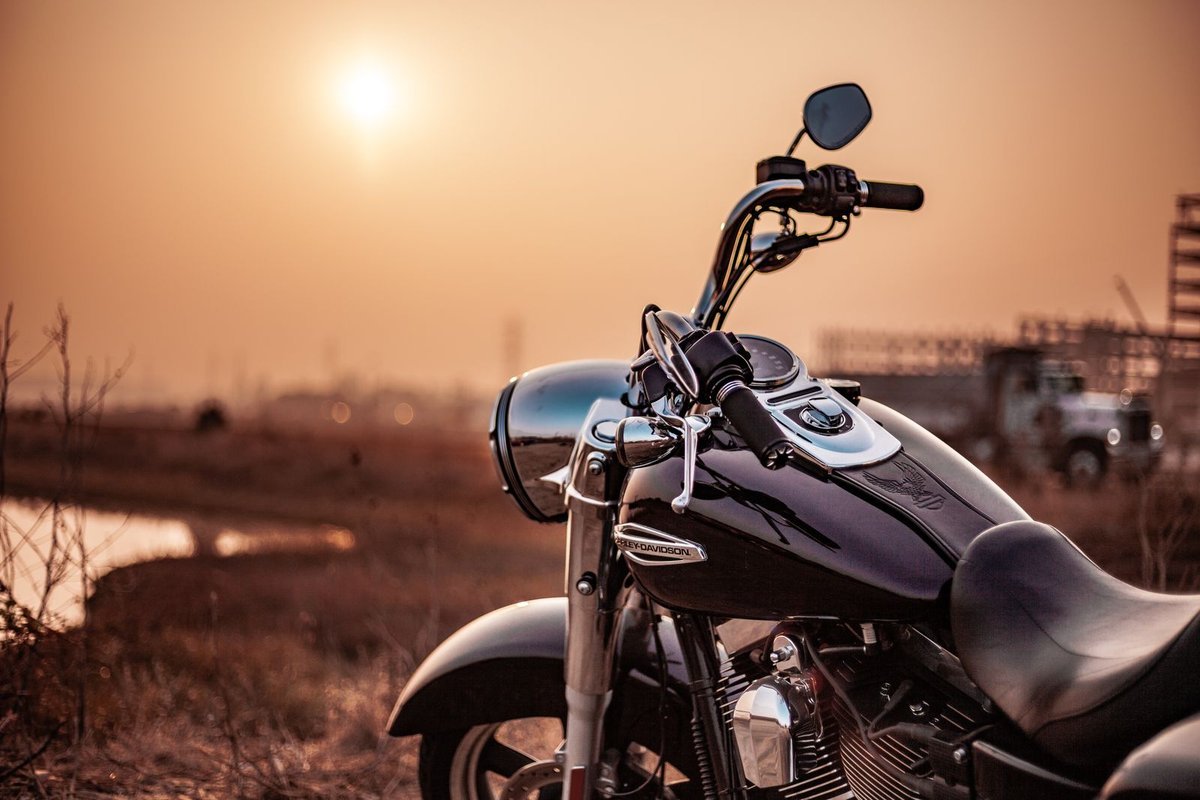
Two-wheel purchases are common in Malaysian commuting. Facilities aimed at motorcycle financing should be compared on tenure, profit rates, and whether insurance packaging is optional or bundled. Check road tax and maintenance budgets so the instalment is not the only cost you can name aloud.
Inspect the unit and confirm seller legitimacy before signing. Financing cannot repair a stolen chassis number problem after the fact, and urgency is a common pressure tactic in informal sales.
Documents and DSR awareness
Prepare identity documents, income evidence, and central credit reports as requested. Know your debt service ratio before applying so declines are not surprises. Disclose existing commitments honestly; hidden obligations surface in bureau data anyway and damage trust in the relationship.
Ask how profit is calculated on early settlement. Surprises here frustrate otherwise careful borrowers who planned to clear balances after a bonus.
Profit expression, early settlement, and deposit trade-offs
Many Islamic facilities disclose two figures: a ceiling profit rate written into the contract and an effective rate actually charged, which may sit lower. Ask which one drives your schedule and under what conditions the bank may move toward the ceiling. Variable structures can shift with a benchmark, so test your budget against a higher figure, not just today’s quote.
Settling before maturity usually triggers an ibra, a rebate on unearned profit that the bank grants under its stated policy. Request a written settlement statement so you see the rebate amount and any fees in actual ringgit. Fixed term placements work the other way round: they reward you for locking money away and charge you, in forgone returns, for withdrawing early.
When a motorcycle is part of the plan, check whether takaful cover is offered as a separate choice or folded into the package. Budget for road tax, servicing, and tyres alongside the instalment itself. Verify the seller and the bike’s documents in person, because no facility can fix a questionable ownership history later.
Sequencing savings, commuting needs, and discretionary wants
Separate emergency savings, essential commuting tools, and discretionary wants before you treat any facility as inevitable this month. If a motorcycle is required for work, model total ownership cost first. If the cash gap is short, compare financing against pausing non-essential spending for one quarter. Household budgeting decides whether a facility is wise; product literacy only helps you ask precise questions of the banker.
Know your debt service ratio and disclose existing commitments honestly. Bureau data surfaces hidden obligations anyway, and early settlement surprises frustrate borrowers who planned to clear balances after a bonus without reading that clause.